
In the rapidly evolving landscape of global hospitality, Hyatt Hotels Corporation has signaled a decisive shift in its business model, tethering its long-term growth prospects to the high-spending, affluent traveler. The company’s third-quarter earnings report, released this past Thursday, paints a picture of a brand that has successfully insulated itself from the volatility of the mid-market segment by doubling down on premium leisure and all-inclusive luxury experiences.
With a revenue per available room (RevPAR) increase of 8.2% in the United States, Hyatt has outperformed market expectations. This growth, which was bolstered by a roughly 50-basis-point lift from the FIFA World Cup, underscores a broader trend: while the average consumer may be feeling the pinch of inflationary pressures, the "premium traveler" remains remarkably resilient.
The Pillars of Performance: A Chronology of Q3 Success
The journey to this quarter’s strong financial showing did not happen in a vacuum. Throughout the fiscal year, Hyatt has been meticulously executing a strategy centered on asset-light expansion and the integration of high-end brands.
- Q1-Q2 Foundation: Hyatt began the year focusing on the stabilization of its loyalty program, World of Hyatt, and the continued integration of the Dream Hotel Group and Mr & Mrs Smith platforms. These acquisitions were calculated moves to capture the boutique and luxury travel segments.
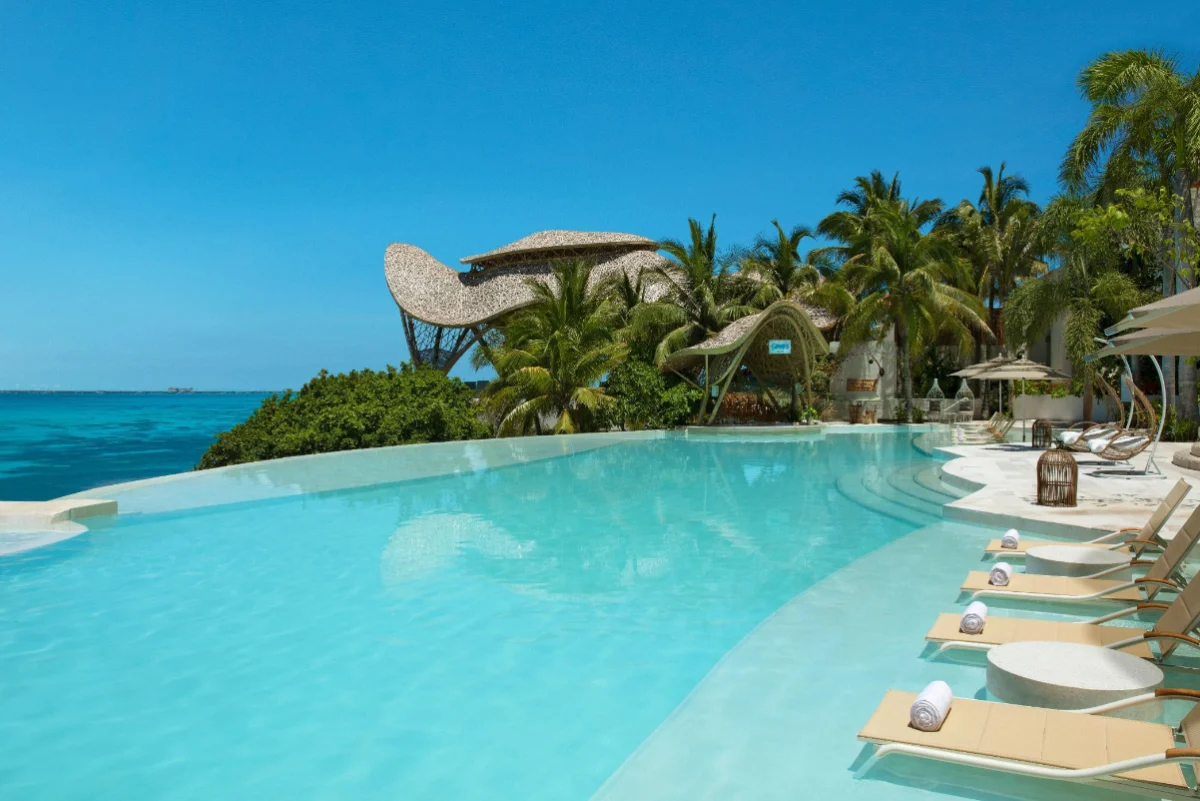
- The Mid-Year Adjustment: In July, Hyatt provided initial guidance for 2026, projecting a conservative RevPAR growth range of 3.5% to 4.5%. However, internal data trends throughout the summer—marked by a surge in demand for all-inclusive resorts in the Caribbean and Mexico, such as the Impression Isla Mujeres by Secrets—suggested that the luxury market was outperforming earlier models.
- The Q3 Surge: By the time the third quarter concluded, it was clear that the company’s assumptions had been too modest. The influx of international travelers and the specific tailwinds from the FIFA World Cup provided the momentum necessary to revise annual expectations upward.
Supporting Data: By the Numbers
Hyatt’s financial health is best reflected in the stark contrast between its previous guidance and its current, bullish outlook. The company reported an adjusted EBITDA of $295 million, a 19% increase when adjusted for the divestment of hotels sold in the prior year.
RevPAR Performance Metrics
The 8.2% increase in U.S. RevPAR is the headline figure, but the internal composition of this growth is equally telling. Luxury leisure properties, particularly those under the "Impression" and "Secrets" banners, saw double-digit growth in average daily rates (ADR).
Updated 2026 Forecast
Hyatt’s decision to raise its full-year RevPAR growth forecast to a range of 5% to 5.5% represents a significant pivot from its July projections. This new guidance sits comfortably above the 4.7% consensus estimate held by Wall Street analysts, signaling a high degree of confidence from leadership regarding the fourth-quarter outlook.
Asset-Light Strategy
A key driver of the 19% EBITDA growth is the company’s aggressive transition toward an asset-light model. By selling off owned real estate and shifting toward management and franchise agreements, Hyatt has reduced its capital intensity. This allows the company to deploy capital more efficiently, focusing on brand acquisition and the expansion of its loyalty ecosystem rather than the maintenance of physical assets.
Official Responses: Leadership’s Vision
During Thursday’s earnings call, CEO Mark Hoplamazian was unequivocal about the source of the company’s current prosperity. When asked by analysts about the potential for a softening in travel demand, Hoplamazian remained dismissive of the bear case.
"Luxury leisure has just remained the juggernaut of growth for us," Hoplamazian stated. He emphasized that the demographic currently driving Hyatt’s occupancy rates—high-net-worth individuals—has shown a persistent demand for "transformational travel experiences."
Hyatt’s leadership team also highlighted that the corporate travel segment is finally showing signs of a return to pre-pandemic parity. However, the company is careful to note that the nature of corporate travel has changed; it is now more frequently blended with leisure, a phenomenon commonly referred to as "bleisure." By positioning its luxury resorts to accommodate both high-level conferences and extended family stays, Hyatt has effectively captured a larger share of the total travel wallet.
The Implications of the "Premium Traveler" Focus
The implications of Hyatt’s current strategy are profound, not only for the company’s shareholders but for the hospitality industry at large.
1. The Death of the "One-Size-Fits-All" Model
Hyatt’s success suggests that the middle-market hotel segment is becoming increasingly bifurcated. Brands that fail to offer a clear value proposition—whether through extreme luxury or extreme efficiency—risk getting squeezed. Hyatt’s aggressive pursuit of the luxury segment is a tacit admission that the most sustainable path to high margins is through the affluent consumer who is less sensitive to price fluctuations.
2. The Role of Loyalty Programs as Ecosystems
The World of Hyatt program is no longer just a rewards scheme; it has become a sophisticated data-collection and customer-retention engine. By integrating boutique brands like Mr & Mrs Smith, Hyatt is keeping affluent travelers within its ecosystem, preventing them from defecting to competitors like Marriott’s Bonvoy or Hilton’s Honors. The ability to cross-sell a high-end luxury resort stay to a business traveler who previously only stayed in Hyatt Regency urban hotels is a powerful driver of lifetime customer value.
3. Geographical Diversification and Geopolitical Risks
While the FIFA World Cup provided a measurable lift to Q3, the reliance on leisure travel brings its own set of risks. The company’s heavy exposure to the Caribbean and Mexico, while lucrative, makes them sensitive to regional climate events and geopolitical instability. However, the geographic spread of the company’s luxury portfolio is designed to mitigate these risks. If one region faces a seasonal or external challenge, the luxury demand in Europe or Asia is designed to offset the decline.
4. The Competitive Landscape
Hyatt’s move forces competitors to react. If Hyatt continues to capture the luxury leisure segment, brands like Hilton and Marriott may be forced to accelerate their own M&A activity in the lifestyle and all-inclusive space. This could lead to a consolidation of smaller, independent luxury boutique brands, as the "Big Three" hotel conglomerates compete to capture the finite supply of unique, high-end properties.
Conclusion: Looking Ahead to 2027
As Hyatt looks toward the end of 2026 and into the following fiscal year, the path forward appears clear. The company is doubling down on what it does best: curate premium, high-touch hospitality experiences for a segment of the population that prioritizes travel over almost all other discretionary spending.
The upward revision of the RevPAR forecast is not merely a numbers game; it is a statement of intent. Hyatt is betting that the "premium traveler" is not a temporary phenomenon but a permanent fixture of the modern global economy. By aligning its operational focus with this demographic, Hyatt has positioned itself as the gold standard for the luxury-leisure era.
For investors, the question remains whether the company can maintain this growth rate as it faces a potentially cooling global economy. However, if the current data is any indication, Hyatt’s strategy—anchored by the strength of its luxury portfolio and its increasingly integrated loyalty ecosystem—is likely to prove as resilient as the travelers it serves. As the industry looks toward the next earnings cycle, all eyes will be on whether the "juggernaut of growth" can sustain its momentum into 2027.
 Reynand Wu
 Sagoh
 Lina Irawan
